

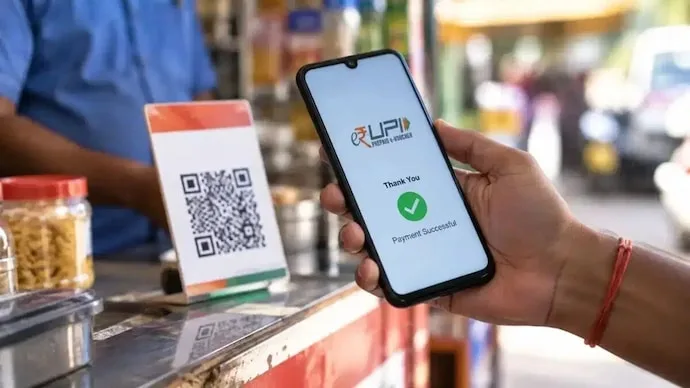
The UPI MDR rollout could be delayed until January 2027, with the National Payments Corporation of India (NPCI) considering requests from merchants, fintech companies and payment firms to postpone the proposed charges until after the festive season.
The proposed 0.4% Merchant Discount Rate (MDR) on UPI transactions above ₹2,000 was scheduled to take effect from October 15, 2026. According to the report, NPCI is discussing the possible deferral with the Finance Ministry and could take a decision shortly.
MDR is a fee paid by merchants to banks for processing digital payments. At 0.4%, the charge would amount to ₹8 on a ₹2,000 transaction and ₹40 on a ₹10,000 transaction.
Why the Rollout Could Be Postponed
Merchant bodies and payments companies have reportedly sought more time, citing concerns over the cost of implementing the new system during the festive sales period.
There are also concerns that additional transaction costs could eventually be passed on to consumers. Industry participants are seeking greater clarity on how MDR will apply to different categories of UPI transactions.
Unlike a relatively uniform card-payment structure, UPI transactions can attract different charges depending on their category, including utility payments, loan repayments and capital market transactions.
This has created uncertainty over which transactions will attract the proposed 0.4% rate and which will continue to be subject to different rates or flat fees.
Loan Repayments and Capital Markets Raise Questions
Capital market participants have also raised concerns about MDR on payments customers make to add funds to their brokerage accounts. The industry has argued that such payments resemble person-to-person transactions and that brokers should not necessarily bear MDR on transactions from which they do not earn revenue.
Loan repayments are another area requiring clarification. The directive reportedly provides for a ₹5 flat fee for loan payments made through auto-debit mandates.
However, when an auto-debit fails because of insufficient balance and a borrower later makes a manual payment, the transaction can be classified differently. NPCI has clarified that such payments should also attract the ₹5 flat fee, but questions remain over how banks and payment aggregators will identify them.
What a Delay Could Mean
A postponement would give merchants, banks and payment companies additional time to prepare their systems and resolve category-wise questions.
For consumers, the immediate impact would be that the proposed 0.4% charge may not begin on October 15 as originally planned. However, whether merchants absorb the additional cost or pass some of it to customers remains unclear.
The report does not establish that the delay has been finalised. NPCI is still considering the proposal, with a decision expected shortly.




Conversation
Be kind and stay on topic. Comments are moderated; abuse, spam and personal attacks are removed. Report a problem